REIT vs InvIT vs real estate
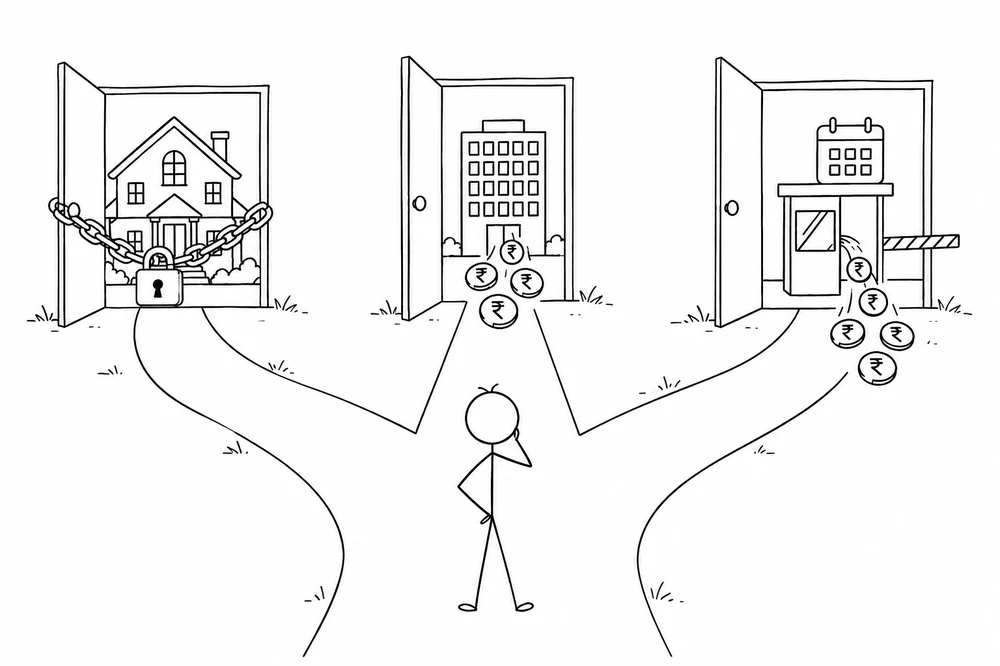
The most common portfolio mistake I see in Indian families is not a bad stock pick. It is concentration: everything in one flat, in one city, in one micro-market, plus a plot somewhere “for the future”.
The three doors, dated
Here is what each option actually offers as of September 2026:
What the table does not show
Yield is not the whole story, and each column hides a risk.
How I would think about the choice
If the goal is income from real assets, the listed trusts win on every practical axis: smaller tickets, real diversification, daily liquidity, professional management, SEBI -mandated payouts of at least 90% of distributable cash.
The most common portfolio mistake I see in Indian families is not a bad stock pick. It is concentration: everything in one flat, in one city, in one micro-market, plus a plot somewhere “for the future”. Owning the home you live in is sensible. It is the second and third property, bought because “real estate always goes up”, that quietly locks a family’s entire net worth into an illiquid, undiversified, low-yielding bet. REITs and InvITs exist precisely for people who want property income without that bet.
The three doors, dated
Here is what each option actually offers as of September 2026:
| Second flat | REIT | InvIT | |
|---|---|---|---|
| You own | One flat, one city | A slice of office parks and malls across cities | A slice of toll roads and power lines |
| Ticket size | Rs 50 lakh and up, plus registration | One unit, a few hundred rupees | One unit, under a hundred |
| Income yield | 2-3% rent, minus society charges and vacancy | ~5.5-7.5% (Embassy ~5.5%, Brookfield ~7.5%) | ~10% (IRB InvIT paid Rs 6.60 per unit in FY26) |
| Selling takes | Months, brokers, and a discount for urgency | Seconds, on NSE | Seconds, on NSE |
| Concentration | Total | Spread across dozens of buildings and tenants | Spread across multiple concessions |
What the table does not show
Yield is not the whole story, and each column hides a risk. The flat’s 2-3% rent looks pathetic until you remember Indians do not buy the second flat for rent; they buy it for appreciation, which is a bet on one micro-market continuing to outperform, with maintenance, property tax and a tenant hunt on the side. The REIT’s 5.5-7.5% distribution is steadier, but the unit price moves with office demand and interest rates; part of the payout is also repayment of debt, which is your own capital coming home. The InvIT’s 10% is the fattest and the most misunderstood: toll road concessions expire, and when the road goes back to the government, so does the income. An InvIT unit is a claim on a wasting asset, priced accordingly.
How I would think about the choice
If the goal is income from real assets, the listed trusts win on every practical axis: smaller tickets, real diversification, daily liquidity, professional management, SEBI-mandated payouts of at least 90% of distributable cash. If the goal is the specific Indian dream of a second door with your name on it, no instrument will substitute, and it helps to be honest that the dream, not the yield, is what is being purchased.
Where I part ways with the family WhatsApp group is the belief that these are substitutes. They are not. A second flat is a concentrated bet on one neighbourhood. A REIT is a salary from an office park. An InvIT is a toll booth annuity with an expiry date. All three are “real assets”; they just pay you in very different currencies of risk.
The family that puts its second Rs 50 lakh into REIT and InvIT units instead of a second flat gives up the house-warming party. What it gets is a statement every quarter, an exit every working day, and the first genuinely diversified property income most Indian families have ever had.